Could Proposed Trust Tax Changes Reshape Family Investment Structures?
The 2026 Federal Budget outlined proposed reforms targeting discretionary trusts and family investment structures.
While the measures have not yet been legislated, the proposed changes would represent one of the more significant shifts to trust taxation in decades if implemented in their current form.
For many business owners, investors, and family groups, the announcement has raised concerns regarding:
- trust distribution strategies,
- long-term tax planning,
- franking credit utilisation,
- and the future flexibility of discretionary trust structures.
What Is the Current Position?
Under the current rules, discretionary trusts generally allow trustees to distribute income between beneficiaries each financial year.
This flexibility has historically allowed families and investment groups to:
- stream income tax-effectively,
- distribute capital gains strategically,
- utilise lower marginal tax rates across family groups,
- and manage long-term asset protection and succession planning objectives.
Trusts also currently retain access to:
- the 50% Capital Gains Tax discount,
- franking credit flow-through,
- and streaming provisions for certain types of income.
For many family groups, discretionary trusts have become a core long-term investment and business structuring vehicle.
What Is Being Proposed?
Under the proposed reforms announced in the Federal Budget:
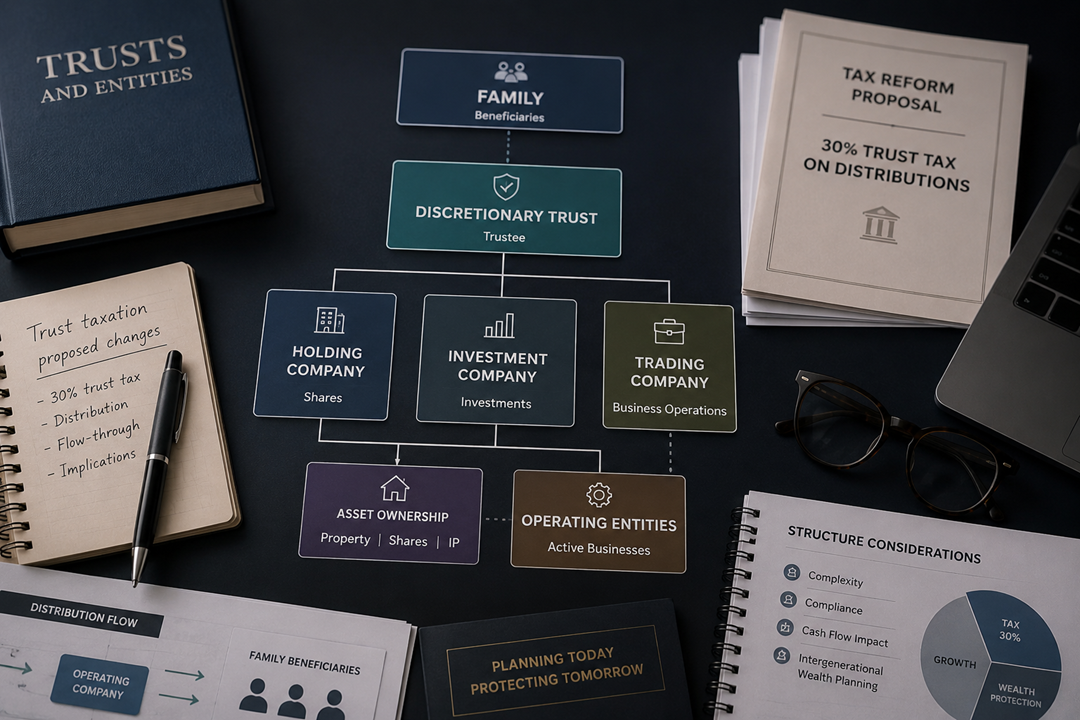
- discretionary trust income would effectively become subject to a minimum 30% tax rate,
- significantly reducing the benefit of distributing income to lower-income beneficiaries.
The proposal is designed to limit the ability of discretionary trusts to achieve materially lower effective tax rates by distributing income across multiple beneficiaries with differing marginal tax rates.
Additional integrity measures are also proposed around:
- trust distributions,
- income streaming arrangements,
- and the use of family trust structures for passive investment income.
The proposed changes are intended to commence from 1 July 2028.
Was Double Taxation Confirmed?
One of the major concerns immediately following the Budget announcement was whether the proposed 30% trust tax would result in outright double taxation.
The Government later clarified that:
- beneficiaries are expected to receive credits for tax already paid at the trust level,
- broadly similar in concept to how franking credits operate for company dividends.
This means the proposal is not intended to simply tax trust income twice in full.
However, there are still significant practical concerns surrounding:
- whether excess credits will be refundable,
- reduced effectiveness of distributing income to lower-income beneficiaries,
- and how bucket company arrangements may operate under the new framework.
As a result, the focus has shifted from concerns about pure double taxation toward concerns regarding:
- reduced tax efficiency,
- credit leakage,
- and reduced flexibility across family groups.
What Is the Purpose Behind the Changes?
The Government’s stated objective is to:
- reduce perceived income-splitting advantages,
- improve integrity within the tax system,
- and align trust taxation more closely with company-style taxation outcomes.
The reforms appear particularly targeted toward:
- large family investment groups,
- passive investment trusts,
- and structures distributing substantial investment income to lower-income beneficiaries.
In practice, the proposals aim to reduce the tax advantage obtained through distributing income across multiple family members at lower marginal tax rates.
Will Existing Trusts Be Impacted?
Unlike the proposed negative gearing changes, broad grandfathering arrangements have not currently been announced for existing discretionary trusts.
This means many existing trust structures may eventually be affected if the legislation proceeds in its current form.
However, the practical impact will vary significantly depending on:
- the type of income generated,
- beneficiary structures,
- existing marginal tax rates,
- and whether franking credits or capital gains form a significant component of trust distributions.
For some family groups already distributing income to beneficiaries taxed above 30%, the overall impact may be relatively limited.
For others relying heavily on lower-income beneficiaries, the changes could materially alter annual tax outcomes.
What About Franking Credits and Capital Gains?
One of the more significant concerns surrounding the proposed reforms is how the new framework may interact with:
- franking credits,
- concessional capital gains treatment,
- and bucket company structures.
Importantly:
- existing concessions are not currently proposed to disappear entirely,
- however the ability to utilise those concessions efficiently across family groups may become more limited.
This may particularly affect:
- investment portfolios held through trusts,
- family groups using bucket company arrangements,
- and retirees receiving franked investment income through discretionary structures.
For many trusts, the issue may not be whether concessions still technically exist, but whether they can still be utilised as effectively after the introduction of minimum trust taxation rules.
What Should Trustees and Investors Be Reviewing?
At this stage, the proposed reforms still lack significant legislative detail, particularly regarding:
- how the minimum tax system will operate in practice,
- how beneficiary tax credits will be applied,
- whether excess credits will be refundable,
- and how the rules will interact with existing trust structures, franking credits, and bucket company arrangements.
As a result, many families and investment groups are currently taking a cautious “wait and review” approach rather than making immediate structural changes.
However, the proposals have already prompted many trustees and investors to begin reviewing:
- trust deed flexibility,
- existing beneficiary structures,
- bucket company arrangements,
- franking credit exposure,
- and long-term succession and investment planning strategies.
Until draft legislation is released, the practical impact for many trust structures remains uncertain.
For now, the key focus for most families is understanding:
- how exposed existing structures may be,
- where future tax inefficiencies could arise,
- and whether flexibility exists to adapt once the final legislation becomes clearer.
At Alchemy Accountants, we assist business owners, investors and family groups in understanding how proposed trust taxation reforms may affect their existing structures and long-term planning strategies.
Whether you operate through a family trust, hold investments in a discretionary trust, or use trust structures as part of your asset protection and succession planning, our team can help you understand the potential impact of the proposed changes and identify opportunities to adapt as further details become available.
We assist with:
- Trust taxation planning
- Trust structure and beneficiary reviews
- Distribution strategy planning
- Asset protection and succession planning
- Investment and wealth structuring advice
- Tax-effective business and family group structures
While the proposed trust tax changes have not yet been legislated, they may significantly affect the way trust income is taxed and distributed in the future. Understanding how the proposed rules may interact with your existing structure can help identify risks and planning opportunities before changes are implemented.
If you would like to discuss how the proposed trust taxation reforms may affect your family trust, investment structure or long-term planning objectives, contact our team for tailored advice.